☎ (928) 242-3192· Serving the White Mountains since 2015Equal Housing OpportunityShawn Wirtz
Shawn J. WirtzREALTOR® · BETTER CALL SHAWN

Category: Buyer Guides

Buyer guides for the White Mountains: how to buy a home, cabin, or land in Show Low, Pinetop-Lakeside, Heber and beyond, from local REALTOR Shawn Wirtz.

  • The ROAD to Housing Act: What the New Federal Housing Law Means in the White Mountains

    The ROAD to Housing Act: What the New Federal Housing Law Means in the White Mountains

    The 21st Century ROAD to Housing Act became law on July 11, 2026 as Public Law 119-101. It’s a long bill, and most of it won’t change anything for a buyer this month. Several pieces line up well with what we see in the White Mountains, though: manufactured homes, one-of-a-kind cabins that are hard to appraise, and lower-priced homes. This is what changes, and which parts are still waiting on federal agencies to write the rules. My main source is the Congressional Research Service summary from Sept. 17, 2026.

    A right to ask for an appraisal reconsideration

    Section 704 requires FHA, VA, USDA and the agency that oversees Fannie Mae and Freddie Mac (FHFA) to make lenders offer a process where a borrower can ask for a reconsideration of value on an appraisal. That matters up here, where a cabin on a few acres or a home with a lot of custom work can be hard to compare. A request doesn’t guarantee a new appraisal or a higher number, as Lower points out, and the agencies still have to put the process in place. My appraisal and pre-approval guide covers how to prepare for an appraisal today.

    Manufactured homes

    • The law raises the base limits on FHA Title I loans for manufactured homes and home improvements, and allows accessory dwelling units under Title I. Loan terms can run up to 30 years. HUD sets the actual dollar limits by notice, and I haven’t seen the new figures published yet.
    • The definition of a manufactured home now covers homes built “with or without a permanent chassis.” HUD still has to write the standards, and states have until July 11, 2027 to certify equal treatment.

    Small FHA loans

    Section 105 lets HUD create a pilot for FHA loans of $100,000 or less on a one- to four-unit primary home. It’s optional for HUD, and it would need to start by July 11, 2027. As of now I haven’t seen it launched. If it does start, it’s aimed at lower-priced homes, where small loan amounts can be harder to finance.

    Limits on large investors

    Starting Jan. 7, 2027, for-profit companies that control 350 or more single-family homes can’t buy more one- and two-unit homes, with exceptions such as homes they build or renovate for sale, build-to-rent, foreclosures and certain senior communities. The rule lasts 15 years, according to CRS and The Close.

    Rural and USDA loans

    The National Association of REALTORS® says the law lets more borrowers assume existing USDA loans and expands USDA financing for homes with an ADU (NAR, Aug. 18, 2026). If you’re considering a USDA loan, check the specific address on the USDA eligibility map before counting on it.

    What it means if you’re buying now

    For the most part, nothing changes at your lender yet. NAR counts more than 100 separate implementation steps in the law, and new programs need funding. The investor limit has a firm start date, and the rest depends on HUD, FHFA and USDA. If you’re financing a manufactured home, a small loan or a property that may be tough to appraise, ask your lender what they’ve been told about timing. My financing guide covers the loan types common up here.

    Local tip:

    If you get a low appraisal on a unique property today, don’t wait for the new rules. Ask your lender about their current reconsideration process and send them the best comparable sales you can find. I can pull recent local sales to back you up.

    Frequently asked questions

    When did the ROAD to Housing Act become law?

    July 11, 2026, as Public Law 119-101 (H.R. 6644).

    Does the ROAD to Housing Act help manufactured home buyers?

    It raises FHA Title I limits for manufactured homes and changes the federal definition to include homes built without a permanent chassis. HUD still has to publish the new limits and write the chassis standards.

    Can I ask for a second look at a low appraisal?

    The law requires FHA, VA, USDA and FHFA to make lenders offer a reconsideration-of-value process, but the agencies are still putting it in place. Many lenders already have a process, so ask yours.

    Financing a cabin, manufactured home or land?

    I’ll point you to the loan types that fit and help you prepare for the appraisal.

    Read the Financing GuideBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county, so please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.
  • New Arizona HOA Laws: What Changed on Sept. 12 for Owners and Buyers

    New Arizona HOA Laws: What Changed on Sept. 12 for Owners and Buyers

    A lot of homes up here sit in an association, from golf communities to small cabin subdivisions and condos. Several Arizona laws from the 2026 session took effect on Sept. 12, the state’s general effective date, and a few of these HOA laws change the rules for owners and buyers. News coverage (for example AZFamily’s) summed them up quickly, so I went to the bill summaries on azleg.gov. One detail got lost in the coverage: the foreclosure change is mostly about condos.

    Foreclosure for unpaid assessments (SB 1246)

    A condominium association can now foreclose only when an owner is 18 months behind or owes $10,000 or more, whichever comes first. The old condo rule was one year or $1,200. Planned communities (the typical subdivision HOA) already had the 18-month or $10,000 rule. For both condos and planned communities, a special assessment of $10,000 or more now falls under the 18-month test only. The governor signed it June 19, 2026. House summary of SB 1246.

    Shade structures (HB 2342)

    A planned community association can’t ban a shade structure in a backyard anymore. That includes umbrellas, awnings, shade sails, gazebos, pergolas and canopies. The association can still set reasonable rules on size, placement and appearance, but those rules can’t block installation, unreasonably raise the cost, or set height or setback limits stricter than local zoning. This one applies to planned communities, not condos. House summary of HB 2342.

    What sellers have to give buyers (HB 2397)

    The resale disclosure process changed. In associations with fewer than 50 units, the seller sends the disclosure electronically within 10 days of accepting an offer. In associations with 50 or more units, the seller notifies the association, and the association has 10 days to send it. The disclosure now includes items like insurance, whether the developer still controls the board, and the percentage of units held by a single owner. The law text caps disclosure fees at $400, plus a $100 rush fee and a $50 update fee, and any title transfer fee has to be disclosed. Laws 2026, Chapter 249.

    Boards have to act fairly (HB 4011)

    Condo and planned community associations now have to use their discretionary powers “neutrally, fairly, without favoritism, and in a nonarbitrary fashion.” House summary of HB 4011.

    Two other bills, SB 1184 and SB 1808, deal with which flags owners can display. If that matters to you, read the text on azleg.gov.

    If you’re buying in an association

    • Read the whole disclosure packet during your due diligence, not just the dues amount.
    • Ask about pending or planned special assessments and the reserve fund.
    • Look at the new insurance and single-owner items. A high share of units owned by one investor can affect financing on condos.
    • Check the rules on what you plan to build or add, like a pergola, fence or shed.

    My guide to HOA communities in the White Mountains goes deeper on what to look for.

    Local tip:

    Some White Mountains subdivisions have a road association instead of a full HOA, and some have nothing at all. Those are different animals. Ask the seller early which one you’re dealing with, because it changes who plows the road and what you’ll pay each year.

    Frequently asked questions

    Can an Arizona HOA foreclose for unpaid dues?

    In a planned community, only if the owner is at least 18 months delinquent or owes $10,000 or more. Since Sept. 12, 2026, condominium associations follow the same 18-month or $10,000 rule instead of one year or $1,200.

    Can my HOA ban a pergola or shade sail?

    Not in a planned community’s backyard, starting Sept. 12, 2026. The association can still set reasonable rules on size, placement and appearance.

    What does an Arizona HOA seller have to give the buyer?

    A resale disclosure with the association’s information, now including insurance, developer control and the share of units owned by one owner. The fee is capped at $400 plus optional rush and update fees.

    Buying in an HOA community?

    I’ll help you read the disclosure packet and ask the right questions before your due diligence ends.

    Read My HOA GuideBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county, so please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo: Woodland Reservoir, Pinetop-Lakeside, by CWanamaker, via Wikimedia Commons, CC BY 3.0.

  • Show Low Homes for Sale: November 2026

    Show Low Homes for Sale: November 2026

    Looking for a home in Show Low? Here is what is on the market this month, how asking prices compare with what homes actually sell for, and the fastest ways to search every listing.

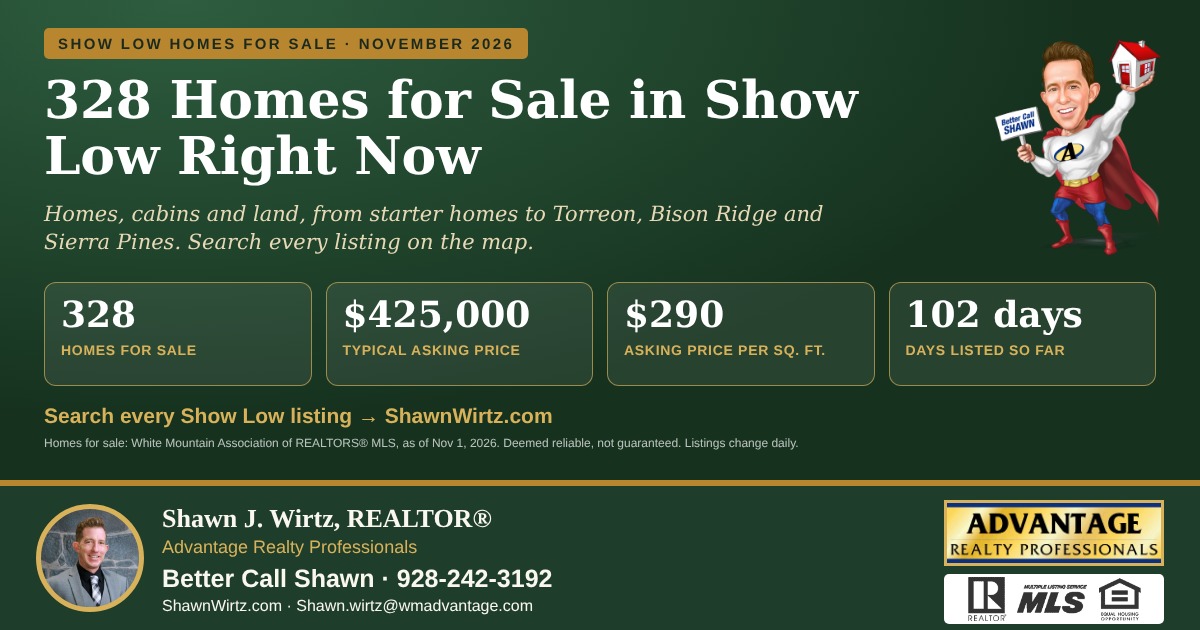
    Show Low AZ homes for sale, November 2026: 328 homes for sale, typical asking price $425,000, $290 asking price per square foot, 102 days listed so far

    Search Every Show Low Listing

    328Homes for sale
    $425,000Typical asking price
    $290Asking price per sq. ft.
    102 daysListed so far

    Show Low homes for sale as of Nov 1, 2026. “Typical” is the middle number: half are higher and half are lower. The listing search is live and updates as homes come on and off the market.

    Asking Prices vs. What Homes Sell For

    Show Low homesTypical priceCount
    For sale now$425,000328 listed
    Sold (past 90 days)$385,000211 sold

    Homes have been selling for about 96% of their final asking price. Fall gives buyers more room to negotiate, and the best-priced homes under $450K still draw attention fast. The $300K–$450K range is selling best.

    Shop Show Low by Price

    Shop Show Low by Neighborhood

    Ask about each community’s HOA rules and fees before you make an offer.

    My Show Low Listings

    PropertyDetailsPriceMLS
    261 S 1st Drive3 bed, 2 bath, 1,506 sq ft$480,000263566
    300 N 5th Drive3 bed, 2 bath, 2,286 sq ft$399,900263547
    9383 Bald Eagle Road1 bed, 1 bath, 784 sq ft$149,900263391
    9880 Texas Lane40 acres$84,900261261

    Prices and status as of November 10, 2026. Tap a listing for photos and details.

    Tips for Buying in Show Low This Fall

    • Get pre-approved before you drive up, so you can move when the right home comes on.
    • Watch new listings weekly. Get my new-listing alerts and hear about homes as soon as they hit the MLS.
    • Compare asking prices with recent sales, not just with other listings. The November market report has the numbers.
    • Sign in to the search to save your favorites and searches.

    Better Call Shawn: (928) 242-3192

    Search every Show Low listing, get alerts, or ask me about any home you see.

    Search Show Low ListingsGet Listing AlertsMarket Report

    Sources: homes for sale and sold homes from the White Mountain Association of REALTORS® MLS, as of Nov 1, 2026 (sold: past 90 days). % of asking: Flexmls Market Trends, Oct 2025–Sep 2026. Listing data deemed reliable but not guaranteed; listings change daily. Shawn J. Wirtz, REALTOR®, Advantage Realty Professionals, Lakeside, AZ. Equal Housing Opportunity.

    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
  • After the Nov. 1 Floods: What White Mountains Owners and Buyers Should Check

    After the Nov. 1 Floods: What White Mountains Owners and Buyers Should Check

    The storms that rolled through over Halloween weekend and into Nov. 1 did real damage up here. Pinetop-Lakeside told residents to shelter in place, the Porter Mountain Road bridge at Highway 260 closed until a structural engineer could inspect it, and some homes reported sewage backing up inside. If you own a home in the White Mountains, or you’re in the middle of buying or selling one, this is a good week to look at three things that are easy to put off: where water goes, what your insurance covers, and what has to be disclosed.

    What happened over the weekend

    The White Mountain Independent’s running storm updates (Nov. 1 and 2, 2026) listed closures and damage across the area:

    • Pinetop-Lakeside: Porter Mountain Road closed between Porter Creek and SR 260, a gas line broke near the Humane Society, and Woodland Road and Woodland Lake Road closed. By 11 a.m. Nov. 2, every road in town limits had reopened except Porter Mountain Road at SR 260, with a pilot car guiding residents along a temporary route.
    • Sewer backups: The Pinetop-Lakeside Sanitary District reported backed-up lines, manhole covers popping up and some homes with sewage coming into the house, and asked residents to limit water use.
    • Show Low: The city closed crossings including 43rd at Bagnal Wash, Show Low Lake Road at SR 260 and Deuce of Clubs at SR 260, and opened a shelter at the City Campus Gym.
    • Snowflake-Taylor: Cottonwood Wash ran high and covered part of SR 77 north of town, and Jake Flake Crossing closed.
    • Washes: Timber Mesa Fire & Medical District made a swift water rescue on Nov. 1 after a vehicle tried to cross a flooded wash and was swept away.

    The Arizona Department of Emergency and Military Affairs said it was sending teams to help the counties assess damage in support of formal disaster declarations. That came on top of the Oct. 30 state emergency Gov. Katie Hobbs declared for Navajo and Coconino counties after the earlier storms, which included a tornado near Heber-Overgaard that damaged more than 20 structures, according to KNAU (Oct. 30, 2026). The state set aside $200,000 for response and recovery.

    If your home took on water

    • Take photos and video before you clean up, including water lines on walls and damaged belongings.
    • Call your insurance company early and ask which part of your policy applies. Storm water coming across the ground is usually treated as flood, and sewage coming up through a drain is a separate coverage.
    • Keep every receipt for pumping, drying and repairs.
    • Stay out of standing water. The sanitary district warned that flood water may carry sewage and can hide open manholes.

    What your policy probably doesn’t cover

    FEMA’s National Flood Insurance Program puts it plainly: most homeowners and renters policies do not cover flood damage. NFIP coverage for a home goes up to $250,000 for the building and $100,000 for contents. Two rules matter for mountain owners:

    • A new NFIP policy usually starts 30 days after you buy it, so buying one the week a storm is forecast won’t help. The wait is waived when the policy is bought as part of making or changing a mortgage.
    • The wait drops to one day when flooding is caused or made worse by a wildfire on federal land and you buy within 60 days of containment. Burn scars on the national forest change how water runs off, so that rule is worth knowing about.

    Sewer and drain backup is its own add-on. NerdWallet (updated July 6, 2026) notes that standard home policies generally won’t pay for a sewer backup, that the water backup endorsement is optional, with limits that often start around $5,000, and that the endorsement still doesn’t cover flooding. I wrote about the fire side of insurance in my wildfire insurance guide. Flood is a separate conversation with your insurance agent.

    Buying or selling after a storm like this

    If you’re shopping in Pinetop-Lakeside, Show Low or Snowflake-Taylor right now:

    • Look up the flood zone. FEMA’s Flood Map Service Center lets you search by address and print a FIRMette. A home outside a mapped flood zone can still take on water, as this weekend showed.
    • Read the disclosure closely. The Arizona Association of REALTORS® notes that the Seller’s Property Disclosure Statement addresses fire, flood and drainage, and sellers have to disclose known material defects.
    • Ask direct questions. Did water get in on Nov. 1? Did the sewer back up? What was repaired, and who did the work?
    • Drive the way in after rain. A low-water crossing between the house and the highway matters as much as the house.
    • Get flood insurance quotes during your inspection period, not after you close.

    Sellers, the same list works in reverse. If water got in on Nov. 1, write down what happened, fix it properly, keep the invoices and put it on the disclosure. A buyer who reads about it on the SPDS is far easier to work with than one who hears about it from a neighbor after closing.

    Local tip:

    Before you list a home or write an offer, pull the FIRMette for the address from FEMA’s map site and save it with your paperwork. It’s free and gives you, your lender and your insurance agent the same map to work from.

    Frequently asked questions

    Does homeowners insurance cover flood damage in Arizona?

    Usually not. FEMA’s FloodSmart site says most homeowners and renters policies do not cover flood damage. Flood coverage is a separate policy, through the National Flood Insurance Program or a private flood insurer.

    How long does a new flood insurance policy take to start?

    Typically 30 days after purchase. The wait is waived when you buy the policy as part of making, increasing, extending or renewing a mortgage, and it drops to one day in a few cases, such as flooding caused or made worse by a wildfire on federal land when you buy within 60 days of the fire’s containment.

    How do I find out if a White Mountains home is in a flood zone?

    Search the address on FEMA’s Flood Map Service Center (msc.fema.gov) and print the FIRMette, a one-page section of the official flood map. Then ask the seller about past water and read the Seller’s Property Disclosure Statement, which covers flood and drainage.

    Questions about a property after the storm?

    If you’re under contract, thinking about listing, or just want to know what to ask about a home after this weekend, call me or send a note.

    Send Me a QuestionBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo © Childress Nature Photography.

  • Propane vs. Electric Heat in the White Mountains: What a Winter Really Costs

    Propane vs. Electric Heat in the White Mountains: What a Winter Really Costs

    At our elevation, heat is one of the biggest costs of owning a home, and when you look at houses up here, how a place is heated matters as much as the square footage. Homes in Show Low, Pinetop-Lakeside and the surrounding towns heat with propane, electricity or a mix of the two, often with a wood stove on the side. I ran the numbers on what a unit of heat costs with each one, using 2026 utility rates and recent propane prices.

    Why our heating bills run high

    Heating degree days measure how cold a place is over a season. Show Low’s airport averages about 4,926 a year, and roughly 2,609 of those fall in December, January and February alone, according to NOAA’s 1991-2020 climate normals. Average December lows are about 23°F. A house here spends a lot of the year with the furnace running.

    What electricity costs

    Show Low is split between two electric providers, and Pinetop-Lakeside is too, so check which one serves a home before you compare bills.

    • Navopache Electric Cooperative: a $36 monthly service charge, then 7.835¢ per kWh for the first 400 kWh and 11.885¢ per kWh above that, under the standard residential rate that took effect Jan. 1, 2026. A purchased-power adjustment and a few small adders can move the final number.
    • APS: on the Fixed Energy Charge plan (R-1), energy runs 12.925¢ per kWh for homes averaging 600 kWh or less a month and up to 15.418¢ for homes averaging 1,000 kWh or more, before adjustors and taxes. APS has a rate case pending, and the Arizona Corporation Commission has to vote by Dec. 31, 2026, so expect new APS rates in early 2027.

    What propane costs

    This one’s harder to pin down. The federal government’s weekly propane survey doesn’t cover Arizona. The closest published number is the Rocky Mountain region, which averaged $2.248 a gallon for residential propane the week of Oct. 5, 2026, against $2.598 nationally, according to the U.S. Energy Information Administration. Those prices leave out taxes. Your actual price depends on your supplier, how much you buy and whether you own the tank, so get a current quote.

    Comparing them on the same scale

    A gallon of propane holds about 91,452 Btu and a kWh holds 3,412 Btu (EIA conversion factors). Adjusting for how efficiently each system turns fuel into heat, this is roughly what one million Btu of delivered heat costs:

    • Propane, 95% efficient furnace, at $2.25/gal: about $25.90
    • Propane, 80% efficient furnace, at $2.25/gal: about $30.75
    • Electric baseboard or furnace, Navopache upper tier: about $34.83
    • Electric baseboard or furnace, APS top R-1 tier: about $45.19
    • Heat pump, Navopache upper tier: about $19.90
    • Heat pump, APS top R-1 tier: about $25.82

    For heat pumps I assumed an efficiency of 1.75, which is the minimum the cold-climate heat pump specification requires at 5°F. Over a whole winter a good cold-climate unit should do better than that, and an older standard heat pump may do worse in a deep cold snap. These are my calculations from the published rates, not utility quotes.

    An example winter

    Say a home burns 500 gallons of propane in a 95% furnace over a winter. That’s about 43.4 million Btu of heat. At $2.25 a gallon, the propane costs about $1,125. Getting the same heat from electric resistance on Navopache’s upper tier would cost about $1,513, or about $1,963 on APS’s top R-1 tier. A heat pump at the 1.75 efficiency above would cost about $865 on Navopache or $1,122 on APS. Your home’s usage will be different, and propane at your supplier’s price could move these numbers either way.

    Rebates in 2026

    The federal energy-efficient home improvement credit ended for equipment placed in service after Dec. 31, 2025, according to the IRS. APS says its AC, smart thermostat and home-checkup rebates are no longer available as of Jan. 1, 2026, and I didn’t find a heat pump rebate on Navopache’s site. Check with your utility before you buy equipment, since programs change.

    What to ask before you buy a home

    • Twelve months of electric and propane bills, so you see a real winter.
    • Whether the propane tank is owned or leased, its size, and who fills it.
    • The age and efficiency rating of the furnace, or the model of the heat pump.
    • Which electric provider serves the address.
    • Whether there’s a wood or pellet stove for backup when the power goes out.

    My fall checklist for mountain homeowners covers getting the heat ready once you’re in.

    Local tip:

    A heat pump only helps if it’s sized and rated for cold climates. If a listing says “heat pump,” ask for the model number and look it up. If you’re on Navopache, also ask about the winter time-of-use rate, which is much cheaper outside peak hours.

    Frequently asked questions

    Is propane or electric heat cheaper in Show Low?

    With 2026 rates and propane near $2.25 a gallon, an efficient propane furnace costs less per unit of heat than electric baseboard, while a cold-climate heat pump can cost less than either. Your propane price and electric provider make the difference.

    Who provides electricity in Show Low and Pinetop-Lakeside?

    Both APS and Navopache Electric Cooperative serve parts of Show Low and Pinetop-Lakeside. Check a recent bill or ask the seller which one serves the home.

    Are there heat pump rebates in Arizona in 2026?

    The federal home improvement tax credit ended after 2025, and APS ended its residential rebates on Jan. 1, 2026. Check with your utility for anything new before you buy.

    Comparing homes this winter?

    I can help you get heating and utility details on any home before you write an offer.

    Get Listing AlertsBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county, so please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo © Childress Nature Photography.

  • Who Plows Your Road? Snow Removal in the White Mountains

    Who Plows Your Road? Snow Removal in the White Mountains

    The first real storm of the season brings the same questions every year: why did the plow go right past my road, and why is there a wall of snow across my driveway again? Both come back to something that’s easy to check before you buy and hard to fix after. Who is responsible for snow removal on your road? In the White Mountains it can be ADOT, a city or town, the county, an HOA, or you and your neighbors.

    Five possible crews, one road

    The White Mountains is a patchwork. Pinetop-Lakeside’s snow removal page lays it out well: ADOT plows Highway 260 through town, the town plows its other public streets, and Navajo County plows the roads it maintains outside town limits. Show Low runs its own crews on city streets. In unincorporated Apache County, including the Concho and Vernon area, the county handles the roads it has designated for maintenance. Anything else (a private road, a subdivision road the county never accepted, a shared driveway easement) is up to the owners.

    The word that matters in every one of these policies is “maintained.” Navajo County’s Roadways 101 page says plainly that not every road in the county is part of the county-maintained system, and Apache County’s engineering page says the county only maintains designated roads.

    How the public crews set priorities

    • Navajo County starts plowing and cindering at about 4 inches of accumulation. The order is major county arterials and school bus routes, then minor collectors, then county residential roads, with county primitive roads last. Clearing the windrows left on county roads generally happens 24 to 48 hours after the storm (Navajo County Snow Removal Policies, checked Nov. 2, 2026).
    • Show Low plans around a typical 6 to 8 inch storm and about 40 inches of snow in an average year. At 3 inches or more it calls out the full crew, 14 pieces of equipment and 28 plow operators on 12-hour shifts. When snow is heavy, high-volume streets go first, collectors second and subdivision streets third (City of Show Low Snow Management plan, 2023-2024 edition).
    • Pinetop-Lakeside starts its snow shift at 2 inches and plows more than 120 lane miles. The town says a typical 4 to 6 inch storm takes at least two days of plowing after the snow stops, and its target for second-priority streets runs from 12 hours (3 to 8 inches) to 36 hours (over 12 inches) (Town of Pinetop-Lakeside “What You Should Know About Snow” page, checked Nov. 2, 2026).

    On a residential street, plan on being later in line.

    The berm at the end of your driveway is yours

    All three local policies say the same thing about driveways. Show Low’s plan says city crews are prohibited from plowing private property or driveways, and notes that each pass builds the berm back up, so wait until the street is widened before you shovel. (Residents with a physician-signed request can ask for berm removal after widening.) Pinetop-Lakeside says a berm can’t be avoided, that opening the driveway is the owner’s responsibility, and asks residents not to shovel snow back into the street. Navajo County puts clearing and cindering driveways on the resident.

    Parking matters too. Pinetop-Lakeside’s Ordinance 19-420 bans parking on any town street from midnight to 7 a.m. between November 1 and April 1, and any time crews are working, so that rule is in effect now.

    Private roads and road associations

    Pinetop-Lakeside’s advice for anyone on a private street is short: get together with your neighbors and have a plan for plowing. The usual setups:

    • An HOA that contracts the plowing and covers it in dues.
    • A road association or recorded road maintenance agreement that splits the cost among the lots that use the road.
    • An informal deal where a neighbor with a blade does it. It works until that neighbor sells.
    • No arrangement at all, which means four-wheel drive and a shovel.

    County takeover is slow. Navajo County can accept some roads as primitive roads under A.R.S. 28-6706, with a request signed by two or more residents with direct access, proof of right-of-way and a survey certification. The county doesn’t upgrade or pave primitive roads (that takes an improvement district under Title 48), and they’re last in the plowing order.

    What I check on a road before you buy

    • The seller’s disclosure. The Arizona REALTORS® Seller’s Property Disclosure Statement (February 2023 version) asks whether road access is maintained by the county, city, an HOA or privately, and if privately, whether there’s a recorded road maintenance agreement. I read that answer closely.
    • The county records. Navajo County has an interactive map of county-maintained roads, and Apache County properties can be looked up on the county GIS. Apache County’s FAQ says roads designated “N” are not county maintained, so on a Concho or Vernon property I confirm the road’s status with the county before we go further.
    • The title report and the neighbors. Recorded easements and road agreements show up in title. Five minutes with a neighbor about last February fills in the rest.

    For a cabin that sits empty in winter, road access also decides how soon someone can check on it. My cabin winterization guide covers the rest of that list, and if you’re shopping for a lot, the land buying checklist walks through access and easements.

    Local tip:

    Save the right numbers before the first storm. Pinetop-Lakeside Public Works is 928-368-8885, the Navajo County Road Yard is 928-532-6080, the City of Show Low’s main line is 928-532-4000, and Apache County’s Round Valley road yard is 928-333-4149. For a medical emergency, call 911.

    Frequently asked questions

    Will the county or town plow my driveway?

    No. Navajo County, Show Low and Pinetop-Lakeside all treat driveways as private property. Clearing the driveway, and the berm the plow leaves across the end of it, is the owner’s job.

    How do I find out if my road is county maintained?

    In Navajo County, check the county’s interactive map of maintained roads or call Public Works at 928-524-4100. In Apache County, look the property up on the county GIS or call the road yard for your area.

    Who pays to plow a private road?

    The owners who use it, usually through an HOA, a road association or a recorded road maintenance agreement. With no agreement, ask the neighbors how it’s handled before you buy.

    Looking at a home or cabin this winter?

    Winter is a good time to see how a road holds up. Set up listing alerts, and I’ll help you check access and road maintenance before you write an offer.

    Set Up Listing AlertsBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo © Childress Nature Photography.

  • Fed Decisions and Mortgage Rates: Why They Don’t Move in Lockstep

    Fed Decisions and Mortgage Rates: Why They Don’t Move in Lockstep

    The Federal Reserve meets eight times a year, and every meeting brings a round of headlines about mortgage rates. A lot of the buyers I talk with assume the Fed sets the rate on their home loan. It doesn’t, and the gap between those two numbers trips people up. Below I walk through what the Fed controls, what moves a 30-year rate, and what the latest numbers mean for a payment on a typical home in Show Low.

    What the Fed actually controls

    The Fed sets a target for the federal funds rate, which is what banks charge each other for overnight loans. That rate feeds quickly into credit cards, home equity lines and other short-term borrowing. It does not directly set a 30-year fixed mortgage.

    At its latest meeting on October 28, 2026, the Fed held its target at 3.75% to 4% on a 10-2 vote, with the two dissenters preferring another quarter-point increase. That followed a quarter-point hike on September 16, when the Fed cited inflation that remains elevated. Its next meeting is December 8-9, and 2027 starts with January 26-27 (Federal Reserve calendar).

    What really moves a 30-year mortgage rate

    Long-term mortgage rates follow the bond market, especially the 10-year Treasury yield, plus a spread lenders add for risk and costs. Bond investors look ahead: where they think inflation, growth and Fed policy will be over years, not this month. So a Fed decision that markets already expected can land with barely a ripple on mortgage rates, while a surprise jobs or inflation report can move them a lot in a day.

    The Fed’s own September 2026 minutes show this. Staff noted that mortgage rates rose a bit more than 10-year Treasury yields between meetings, and that 2- to 10-year yields climbed about 35 basis points, tied to things like geopolitical developments and heavy borrowing for AI infrastructure. None of that is a Fed vote.

    A recent example of the two moving apart

    In September 2024 the Fed cut its target by half a point. Many buyers expected mortgage rates to drop right along with it. The 30-year average was 6.08% on September 26, 2024 (Freddie Mac), its lowest level in two years. From there it climbed, and by October 31, 2024 the average was 6.72%, its fifth straight weekly increase, as strong economic data had markets expecting smaller Fed cuts. So the Fed lowered its rate while the cost of a 30-year home loan went up over the following weeks.

    Where rates sit now, and what that means for a Show Low payment

    Freddie Mac’s survey for October 29, 2026 put the 30-year fixed at 7.24%, down from 7.32% the week before and up from 6.17% a year earlier. The 15-year averaged 6.60%.

    To put that in local terms, my Show Low market report shows a typical sold price of $392,500 for homes that closed in the 90 days before October 2, 2026. With 10% down, that is a loan of about $353,250. Principal and interest only (taxes, insurance and any HOA come on top):

    • At 7.24%: about $2,407 a month
    • At 6.99% (a quarter point lower): about $2,348, roughly $59 less
    • At 6.74% (a half point lower): about $2,289, roughly $118 less
    • At last year’s 6.17%: about $2,157, roughly $250 less than today

    Those are my calculations from the Freddie Mac averages, not a quote. Your rate depends on credit, down payment, loan type and the property itself, and cabins, manufactured homes and second homes can price differently from a primary residence in town.

    What I’d watch instead of the Fed headline

    • The weekly Freddie Mac average, released Thursdays. It is the cleanest read on where 30-year rates are trending.
    • Inflation and jobs reports. They often move mortgage rates more than the Fed meeting does, because they change what bond investors expect.
    • What the Fed says, not only what it does. Its statement and projections hint at the path ahead, and markets react to that.
    • Your own lock window. If you are under contract, the rate you lock matters far more than any national average. Talk with your lender about how long the lock lasts and what an extension costs.

    Up here the local market matters as much as the rate. Show Low homes sold for 96.2% of their last asking price over the 12 months through September 2026, and the average home took 130 days to sell, per the same market report. That leaves room to negotiate, including asking a seller for credits toward a rate buydown.

    Local tip:

    If you are waiting for rates to fall before buying, set up listing alerts now for the town and price range you want. Show Low homes are taking longer to sell than a year ago, so you can learn what is out there and what it sells for, and be ready to move when the numbers work for you.

    Frequently asked questions

    Does the Fed set mortgage rates?

    No. The Fed sets a target for the overnight federal funds rate. Thirty-year mortgage rates follow the bond market, especially the 10-year Treasury yield, plus a lender spread. Fed policy influences those markets, but the two rates often move at different times and by different amounts.

    If the Fed cuts rates, should I wait to buy?

    Not automatically. Mortgage rates often move before the Fed acts, and they can rise after a cut, as they did in the fall of 2024. Watch the weekly Freddie Mac average and your own budget rather than the meeting date.

    How much does a quarter point change a payment in Show Low?

    On a $353,250 loan, about 10% down on the typical recent Show Low sale price of $392,500, a quarter point is roughly $59 a month in principal and interest at today’s rate levels. Taxes, insurance and HOA dues are extra.

    Want to run the numbers on a home up here?

    I can walk you through what a payment looks like on the homes you’re watching and connect the dots with your lender’s quote. Start with financing basics or grab a time to talk.

    White Mountains financing guideBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo © Childress Nature Photography.

  • Living Near Sunrise Park Resort: How Far Each White Mountains Town Is From the Lifts

    Living Near Sunrise Park Resort: How Far Each White Mountains Town Is From the Lifts

    Ski season is close, and if you’re shopping for a place up here, the distance to Sunrise is a fair question to ask about any house. Sunrise Park Resort bills itself as Arizona’s largest ski resort, and it sits east of Pinetop-Lakeside off State Route 273. If skiing is a big reason you’re buying, the drive to the lifts matters as much as the square footage. Below are the drive distances from each White Mountains town and what homes have been selling for in the towns closest to the mountain.

    Sunrise in a few numbers

    Sunrise is owned and operated by the White Mountain Apache Tribe on the Fort Apache Indian Reservation. The resort lists 67 trails and 8 lifts across three mountains on its winter page, and the base area sits at about 9,200 feet (per Wikipedia’s resort summary).

    • Last season: Sunrise opened Friday, Dec. 12, 2025, according to the resort’s Dec. 9, 2025 press release, and closed for the season on March 20, 2026 (SnowBrains, March 24, 2026).
    • This season: As of Oct. 19, 2026, Sunrise had not announced its 2026-27 opening day. OnTheSnow lists a projected opening of Dec. 11, and it says projected dates are not official.
    • Snowmaking: The resort added 24 new snowmaking units before last season, per the same December 2025 release. That matters in a dry year, since early terrain depends on it.
    • Tickets: Last season’s day tickets used dynamic pricing starting at $25, per that release. Check the resort’s ticket page for this season’s prices.

    How far each town is from the lifts

    Every route ends the same way: US 260 to the SR 273 turnoff, then south a few miles to the lodge. Sunrise’s own directions page puts the turnoff about 40 minutes past Pinetop and about 20 minutes from Springerville. For door-to-resort mileage, I ran each town center through OpenStreetMap’s routing service on Oct. 19, 2026. These are dry-road numbers, so treat them as a floor on a snow day:

    • Greer: about 20 miles
    • Eagar: about 25 miles
    • Springerville: about 27 miles
    • Pinetop-Lakeside: about 33 miles
    • Show Low: about 42 miles
    • Snowflake: about 61 miles
    • Concho: about 69 miles
    • Heber-Overgaard (Heber): about 79 miles

    A home on the east side of Pinetop-Lakeside, toward Hon-Dah, cuts a few miles off the Pinetop figure. A home on the far west side of Show Low adds some. On storm days, ADOT’s AZ 511 site shows road conditions and highway cameras before you leave.

    What homes cost in towns within about 45 miles of Sunrise

    These are the latest closed-sale numbers from my White Mountains market reports, pulled from WMAR/ARMLS via FlexMLS as of Oct. 2, 2026:

    • Springerville-Eagar: $275,000 median sold price, $192 per square foot, 74 median days to sell (sold homes), 51 homes sold (past 6 months)
    • Greer: $418,000 median sold price, $334 per square foot, 85 median days to sell (sold homes), 19 homes sold (past 6 months)
    • Show Low: $392,500 median sold price, $295 per square foot, 84 median days to sell (sold homes), 200 homes sold (past 90 days)
    • Pinetop-Lakeside: $465,000 median sold price, $291 per square foot, 69 median days to sell (sold homes), 174 homes sold (past 90 days)

    Round Valley is worth a look for skiers. Eagar and Springerville are closer to the SR 273 turnoff than Pinetop-Lakeside, and they had the lowest price per square foot on that list. At those medians, a 1,500-square-foot home works out to roughly $288,000 in Springerville-Eagar and roughly $437,000 in Pinetop-Lakeside. That’s simple math on medians, not a value for any particular house, but it shows the spread.

    Greer is the closest town to the lifts and sits around 8,400 feet. It’s also a small market. Nineteen sales in six months means fewer cabins to choose from at any one time, so buyers who want Greer usually need some patience and a search that alerts them the day something lists.

    What to check on a home you’ll use in ski season

    • Who plows the road. County-maintained, a road association, or nobody. Ask before you write an offer, and ask how soon after a storm the plow usually comes.
    • The driveway. A north-facing driveway on a slope can hold ice for weeks. Look at it with winter in mind, even if you’re touring in fall.
    • Heat and fuel. Find out whether the home runs on propane, electric or wood, and whether a delivery truck can reach the tank after a snow.
    • Weeks when it sits empty. A part-time ski cabin needs a plan for pipes and heat between trips. My cabin winterization guide walks through it.
    • Rental plans. If you hope to rent it on ski weekends, read the town or county rules and any HOA CC&Rs before you buy, not after.
    Local tip:

    If you’re serious about a house for ski season, drive from it to the SR 273 turnoff early on a winter morning before you commit. The same drive can take much longer after a storm, and one trip will tell you a lot about the road, the plowing and the driveway.

    Frequently asked questions

    When does Sunrise Park Resort open for the 2026-27 season?

    As of Oct. 19, 2026, Sunrise had not announced an opening day. Last season it opened Dec. 12, 2025, and OnTheSnow projects Dec. 11 this year, though that date is not official. Check the resort’s website for the confirmed date.

    Which White Mountains town is closest to Sunrise?

    Greer, at about 20 miles by OpenStreetMap routing. Eagar and Springerville are about 25 to 27 miles away, Pinetop-Lakeside about 33 miles and Show Low about 42 miles, all on dry roads.

    Can I rent out a cabin near Sunrise during ski season?

    It depends on the property. Town and county rules and HOA CC&Rs vary, so check them before you buy if rental income is part of your plan, and talk with a tax professional about how rental income is taxed.

    Want a home within an hour of the lifts?

    I can set up a search for Greer, Springerville-Eagar and Pinetop-Lakeside homes and cabins and send you new listings the day they hit the market.

    Set Up Listing AlertsBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.

    Header photo © Childress Nature Photography.

  • Home Insurance in Wildfire Country: What White Mountains Buyers and Owners Should Know

    Home Insurance in Wildfire Country: What White Mountains Buyers and Owners Should Know

    If you’re buying a home or cabin under the pines up here, wildfire home insurance belongs near the top of your list, right next to the inspection. Arizona’s market is in better shape than California’s or Florida’s, but Navajo County had a rough stretch a few years ago and the state has spent the last two years studying why. This is what the numbers show, what Arizona has done so far, and what I tell buyers and owners in Show Low, Pinetop-Lakeside and Heber-Overgaard to do about it.

    What the numbers say

    The best public data I’ve found is a University of Arizona Cooperative Extension report by Dari Duval, published in October 2025. It tracks the share of homeowners policies that insurers chose not to renew, county by county:

    • Navajo County: 4.8% in 2022, the highest county rate in the report, then back down to 0.9% in 2023.
    • Apache County: between 0.5% and 1.2% every year from 2018 through 2023.
    • Arizona statewide: 0.8% in 2023.

    The report is careful to say the data can’t prove wildfire caused those non-renewals, and it doesn’t show insurers’ reasons. Still, anyone who was here in 2002 understands why carriers watch this area. The Rodeo-Chediski Fire burned almost 470,000 acres, destroyed nearly 200 structures (most of them homes) and kept 30,000 people out of their homes for up to two weeks, according to the White Mountain Independent, “Remembering the Rodeo-Chediski Fire 20 years later” (June 17, 2022).

    What Arizona has done so far

    • The Arizona Department of Insurance and Financial Institutions (DIFI) formed a Resiliency and Mitigation Council to look at wildfire and insurance access. The Central Arizona Association of REALTORS® reported in January 2026 on the council’s December 2025 report. Arizona doesn’t have a state FAIR plan.
    • In 2025 the Legislature passed HB 2054, which created a fire insurance review task force and calls for better reporting on wildfire risk and fire losses. It also passed HB 2201, which lets utilities, including electric co-ops like Navopache, file wildfire mitigation plans (Arizona House news release, April 17, 2026).
    • DIFI ordered insurers to report policy-level data, including renewal and termination dates, for homes in the state’s heightened wildfire-risk areas for 2025 and 2026. The 2025 data was due April 1, 2026 (summary of the data call).

    None of that changes anyone’s premium this winter. It does mean the state will soon have much better numbers on who is getting dropped and where.

    If you’re buying: get a quote during your inspection period

    In the standard Arizona REALTORS® purchase contract, insurance is one of the things you check during your inspection period. Don’t wait for your lender to bring it up. On a house that backs up to national forest, I want buyers holding a written quote within the first few days. These are the details carriers tend to ask about up here:

    • Roof material and age
    • Distance to the nearest fire station and hydrant
    • Trees, brush and woodpiles close to the house
    • Wood decks and fences attached to the structure
    • Whether the neighborhood is a recognized Firewise USA site

    If you’re looking at property next to forest land, my guide to homes bordering national forest covers the trade-offs, and the home inspection guide walks through the inspection timeline.

    If you already own: how to keep your policy

    • Know the notice rule. DIFI says an insurer that won’t renew must give you at least 30 days’ notice before the policy period ends (DIFI FAQ). That isn’t much time, so open every renewal letter the day it shows up.
    • Do the work and keep proof. Clear needles off the roof and out of the gutters, limb up trees, move firewood away from the house and take dated photos. A carrier may or may not give you credit, but you want that record if one asks.
    • Talk to your neighbors about Firewise. Arizona has 154 recognized Firewise USA sites, and the state Department of Forestry and Fire Management works with HOAs and neighborhoods to set one up. Navajo and Apache counties are in its Southwest, Central, and Northeast Zone (DFFM Firewise page).
    • Shop early. If a non-renewal notice arrives, start calling that day. An independent insurance agent can quote several carriers at once, and if the standard companies pass, a surplus lines policy may still satisfy your lender. Read how it pays claims before you sign.
    Local tip:

    When you’re serious about a cabin, ask the seller for a copy of their current insurance declarations page. It shows what a carrier was willing to write on that exact house this year and what it cost, which gives your own insurance agent a real starting point. If the seller switched carriers recently, ask why.

    Frequently asked questions

    Does Arizona have a FAIR plan for homes that can’t get regular insurance?

    No. Arizona doesn’t have a state FAIR plan for homeowners. Homes that standard carriers turn down are usually placed with surplus lines insurers, which often cost more and can cover less, so read the policy before you rely on it.

    How much notice does an insurer have to give before it drops my homeowners policy?

    According to the Arizona Department of Insurance and Financial Institutions, an insurer must give at least 30 days’ notice before the end of the policy period if it won’t renew. The same applies when renewal depends on lower limits or removed coverage.

    Will living in a Firewise USA community lower my premium?

    It isn’t guaranteed. Firewise recognition shows your neighborhood does ongoing wildfire work. Ask every carrier that quotes you whether it gives credit for that or for the mitigation you’ve done on your own lot.

    Buying near the forest?

    I can help you get insurance questions answered before your inspection period runs out, and show you homes where the numbers still work.

    Book a CallBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.
  • Show Low Airport Upgrades: What They Mean for Flying In and Out of the White Mountains

    Show Low Airport Upgrades: What They Mean for Flying In and Out of the White Mountains

    If you’re thinking about a home up here and still need to get to Phoenix or beyond, how easy it is to fly in and out matters. On Oct. 6 the Show Low Aviation Advisory Committee gave the City Council its annual update on Show Low Regional Airport. A lot is going on out there. The details below come from the White Mountain Independent’s report on that meeting.

    How the airline is doing

    Contour Airlines flies scheduled service between Show Low and Phoenix Sky Harbor. In August it carried 2,045 passengers, with 69.3% of flights arriving on time, 64.4% departing on time and a 94.4% completion rate (six cancellations). Committee vice chairman David Murray pointed out that reliability affects more than travel plans. With the previous airline, a canceled flight could mean 60 to 90 patients had to be rescheduled when a visiting specialist couldn’t get here.

    What’s being built or planned

    • Terminal expansion: out to bid.
    • FAA inspection: the airport passed its Part 139 certification inspection, held Aug. 17 to 19.
    • Taxiway B and fuel: Taxiway B improvements and a new AVGAS fuel truck were approved in the fiscal 2027 budget.
    • Runway lighting: two ADOT grants will pay for new LED runway signs plus approach lights and runway end identifier lights on Runway 7-25. That work is out to bid.
    • New or expanded runway: an environmental assessment is underway and scheduled to finish in March 2027.
    • Already done: a bigger parking lot, a fresh coat of paint on the terminal, and new roofs on the city hangar and the Bureau of Indian Affairs building.

    Hangars and private flying

    The city put out a request for proposals in December 2025, received three and selected one. Several new leases have been signed, and privately built hangars have gone up on the field. If you fly your own plane and are weighing a move to the White Mountains, hangar space is worth asking about early.

    What it means if you’re buying here

    For second-home owners and people who still work part of the week in the Valley, a scheduled flight to Sky Harbor is an option besides the drive down. That drive takes about three hours. Keep in mind that airport projects move at the FAA’s pace, so I wouldn’t buy a house counting on a project being finished by a certain date. If you’re looking at homes near the airport, note that the update mentioned a noise abatement sign near the Runway 25 end. Drive the area at a few different times of day before you write an offer.

    Local tip:

    If being close to the airport (or far from it) matters to you, tell me up front. I can set up a search around it and pull the zoning on any parcel you’re considering so there are no surprises about what can be built nearby.

    Frequently asked questions

    Does Show Low have commercial flights?

    Yes. Contour Airlines flies scheduled service between Show Low Regional Airport and Phoenix Sky Harbor. Check the airline for current schedules and fares.

    Is the Show Low airport terminal being expanded?

    Yes. As of the Oct. 6, 2026 update to the City Council, the terminal expansion was out to bid. No completion date was given.

    When will Show Low get a new or expanded runway?

    Runway 4-22 already serves as the airport’s crosswind runway. The environmental assessment for a new or expanded runway is scheduled to finish in March 2027. Construction timing depends on federal review and funding after that.

    Want to live near the airport, or well away from it?

    Tell me what matters and I’ll set up a search that fits.

    See Show Low HomesBetter Call Shawn
    Shawn J. Wirtz, REALTOR
    Shawn J. Wirtz, REALTOR®
    Advantage Realty Professionals
    Advantage Realty ProfessionalsREALTOR, MLS, Equal Housing Opportunity
    Disclaimer: This guide is provided for general informational purposes only and is not legal, tax, financial, insurance, engineering, or professional advice. Laws, fees, regulations, and market conditions change and vary by property, town, and county. Please verify the details that matter to you with the appropriate agency or a licensed professional before making a decision. Information is believed to be reliable but is not guaranteed. Shawn J. Wirtz, REALTOR® · Advantage Realty Professionals · Equal Housing Opportunity.